Your Local Mortgage Lender
Located in Destrehan, Louisiana
Personalized Mortgage Experience
Brian Maurice offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Destrehan, Louisiana .
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
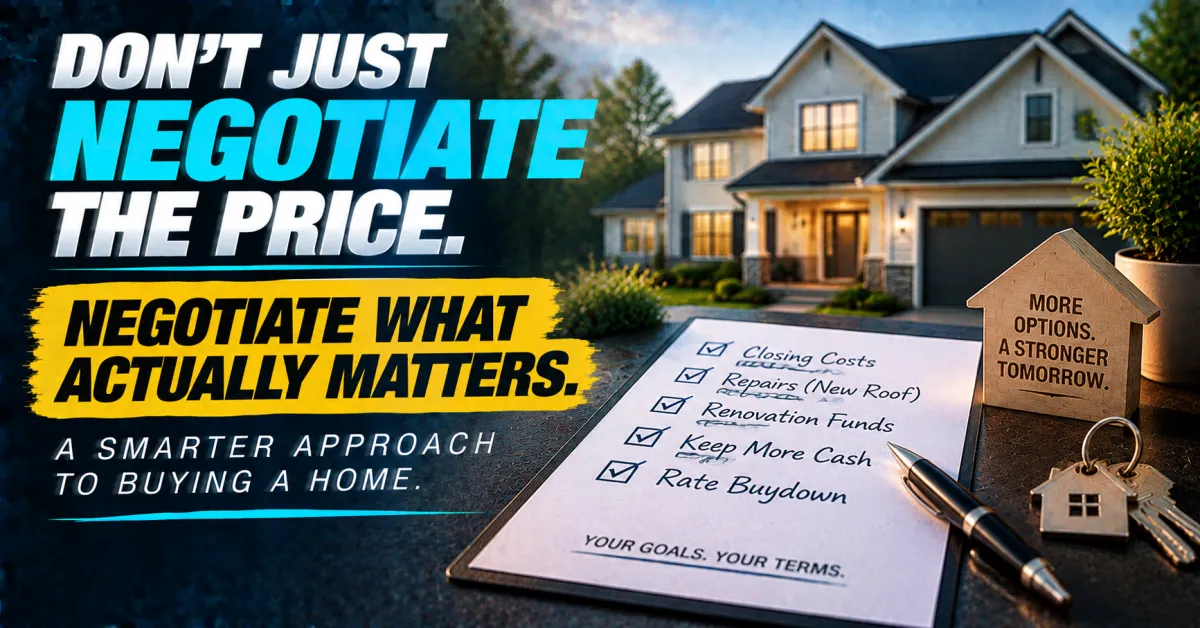
Do Not Just Negotiate the Price When Buying a Home and Here Is What to Focus on Instead
The Negotiating Mindset That Produces Better Outcomes Than Chasing a Lower Number
When buyers think about negotiating a home purchase the conversation almost always starts and ends with price. Get the seller to come down. That is the goal. Brian Maurice wants buyers to think differently because the best deal is not always the lowest price. It is the deal that puts you in the best position after you buy it.
What Actually Matters Depends on Your Specific Situation
Every buyer's biggest obstacle is different and the right negotiating focus should reflect that rather than following a generic script.
For some buyers closing costs are the most pressing concern. Cash to close is the constraint and a seller contribution that reduces what needs to come to the table at closing is worth more in practical terms than an equivalent price reduction would be.
For buyers purchasing a home with a roof that is approaching end of life a seller concession toward roof replacement or a repair credit can save thousands on homeowners insurance annually going forward. A new roof is not just a comfort item. In many markets it materially changes the insurance premium and the insurability of the property. Negotiating that specifically rather than simply asking for a price reduction can produce a better long-term financial outcome.
For buyers who want to renovate and have a vision for what the home becomes a renovation credit keeps that money in their hands to deploy toward improvements rather than requiring them to save up after closing while living in a home that is not yet what they envisioned.
For a buyer with a baby coming the priority might be something entirely different. Keeping more cash in the bank after closing matters more than almost anything else when a family is about to grow and expenses are unpredictable. A seller contribution that preserves liquidity is more valuable in that situation than knocking ten thousand dollars off the purchase price.
And a rate buydown funded by seller concessions can lower the monthly payment by hundreds of dollars for the life of the loan or for the critical early years when the financial adjustment to homeownership is most significant.
Why Right Now Is the Time to Get Creative
Sellers are much more willing to give concessions in the current market than they have been in years. Homes are sitting longer. Price adjustments are happening. The negotiating dynamic has shifted toward buyers in ways that create genuine room for creative structuring that simply was not available during the peak seller's market.
Getting creative with how that flexibility is used rather than defaulting to a price reduction produces deals that fit the buyer's actual situation rather than simply a lower number on the contract.
What the Right Team Makes Possible
The best concession strategy requires a lender who knows which programs allow which types of contributions and at what limits, and an agent who understands how to structure an offer that captures maximum value for the buyer without unnecessarily alienating the seller. Make sure you work with an agent and lender who make you their priority.
Reach out to Brian Maurice to run the numbers on what the right concession strategy looks like for your specific situation before your next offer is written.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
NAR.realtor
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
